For years, the discourse on revitalising Nepal’s economic performance has centred on boosting its exports. As for the latest fiscal year, imports account for 87 percent of Nepal’s total trade, compared to just 13 percent for exports. But the last couple of years have been encouraging. Nepal experienced an impressive 77.8 percent increase in year-on-year export revenue from FY 2023-24 to 2024-25. Against this backdrop, it is important to ask: Have high numbers addressed the economic frustrations of the populace?
In this piece, I argue that the actual goal should be to build domestic economic resilience. Strengthening Nepal’s productive capacity and economic environment is a far more pertinent goal, which will undoubtedly be reflected (if successful) not just in trade figures, but in daily life.
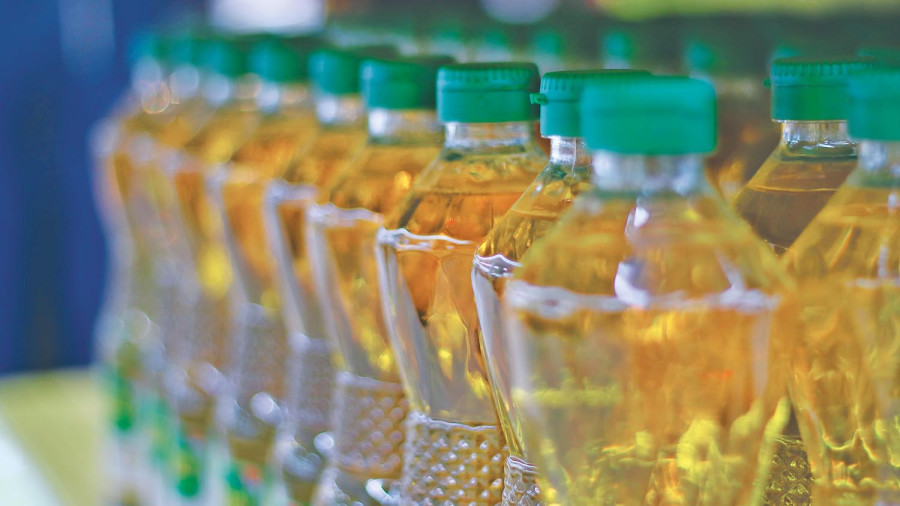
One may just need to take a closer look at our trade statistics to understand my proposition. 40.8 percent of our total export share is attributed to refined soybean oil, with India as the major destination. It is a product that has seen an exponential increase since India imposed an import duty on refined edible oils from non-South Asian Free Trade Area (SAFTA) countries at 35.75 percent in 2024. Crucially, Nepal, as a SAFTA member and least developed country, benefits from this preferential access to the Indian market with zero or preferential duty rates on its refined oil exports to India. Given that our domestic production of raw soybean is reported to be insufficient to even meet local demand, and that Nepal has seen a surge in crude edible oil imports from countries like Argentina, Brazil and Ukraine in the same time period, the available evidence strongly suggests tariff arbitrage has been a major driver of our export growth.
Tariff arbitrage is the idea of avoiding higher import tariffs by rerouting supply chains through low-tariff countries. Crude oil is imported, then refined domestically and exported duty-free to India. The resulting tariff differential gives Nepal-based refiners a significant advantage in supplying the Indian market. If the objective were simply to increase headline export figures year-on-year, this ‘strategy’ could reasonably be considered a success. But export growth alone tells us little about the durability of the underlying competitive advantage or the domestic value it creates.
The first reason for caution is the instability of this advantage. Because Nepal’s competitiveness in this trade depends substantially on preferential access to the Indian market, changes in India’s tariff policy can rapidly erode or restore Nepal’s relative advantage. Crucially, this is not a mere hypothetical. Between 2018 and 2021, Nepal’s soybean oil exports to India exploded from a negligible 1,300 tonnes to a peak of 332,000 tonnes. But when New Delhi slashed its refined oil import duties down to 12.5 percent by 2023, the advantage evaporated. Nepalese exports collapsed to just 5,600 tonnes.
The moment India raised duties back up in 2024, exports promptly rebounded to 65,000 tonnes. While the timing alone does not establish causality, the repeated expansion, contraction and recovery are consistent with an export advantage that is highly sensitive to India’s tariff regime. What seems to be a clever trick on our part leaves Indian regulators unhappy, who have repeatedly called for intervention. Should any policy change occur again, the Nepali export industry will surely feel it. Therefore, the experience of the past several years cautions against interpreting tariff-sensitive export growth as evidence of a durable improvement in Nepal’s underlying competitiveness.
Economic logic would suggest that an industry capable of almost half the exports of a country should be a significant employer, producer and a real engine of growth. Is the scale of the oil refining sector’s export figures proportional to its domestic value creation? Nepal Vegetable Ghee and Oil Manufacturers Association reports that approximately 15,000 people are employed directly and indirectly across 27 edible oil manufacturing plants in Nepal. Since the principal raw material is imported, concerns about how many productive linkages it generates and whether those benefits justify an industry whose competitiveness can change dramatically with India’s tariff policy are also relevant.
Experts opine that the conversion of crude oil to refined oil does not add much value to the finished export. Subsequently, recent concerns over whether local processing satisfies applicable value-addition requirements under SAFTA add another layer of risk. Nepal already faces market-access restrictions in India over issues such as standards and quality control; for example, more than 700,000 kgs of processed Nepali tea remained unsold in factory warehouses after India introduced new quality-testing requirements, while dozens of factories in Eastern Nepal suspended operations. Questions over compliance with preferential-trade requirements could create further friction in a relationship on which 61 percent of Nepal’s trade depends.
On a fundamental level, this instance is about the state’s role in the economic activity it permits, if not actively promotes, through both policy and passive neglect. It must be considered that the tariff structure may be shaping investment itself. When differences in tariff treatment make the processing of imported inputs particularly profitable, capital may be drawn towards activities whose competitiveness depends more on preferential market access than on expanding Nepal’s underlying agricultural or productive capacity. The contrast with Nepal’s established agricultural and niche exports is therefore instructive. Tea, ginger, cardamom and other products have stronger linkages to domestic producers, yet they face a different set of constraints involving market access, standards and certification, financing, and quality control. This has resulted in tea, jute and herbs together representing just 5 percent of the total share of exports.
Nepal’s domestic production policies should focus on addressing bottlenecks that prevent existing domestic industries from becoming more competitive: improving standards and certification, strengthening quality-control infrastructure, expanding processing and value addition, improving access to finance, and using trade diplomacy to reduce unpredictable non-tariff barriers. Such steps could strengthen industries whose growth is more directly linked to Nepali producers and workers, while also diversifying Nepal’s export base and reducing its dependence on a narrow set of products and markets.
Furthermore, Nepal should not reject industries that benefit from preferential trade arrangements, but understand that any benefit from such opportunities is temporary. The path to securing permanent resilience lies in simultaneously addressing the standards, financing, productivity and market-access constraints that prevent domestically rooted industries from becoming more competitive.
Few aspirations run as deep in the Nepali consciousness as the dream of true economic self-reliance. Years of calcified inefficiencies, inabilities and interdependencies have distorted our understanding and strategies for long-term economic growth. The aforementioned concept of self-reliance cannot precede resilience.
To conclude, a more meaningful assessment of export performance should ask not only how much Nepal exports, but how much domestic value those exports create, how deeply they are linked to employment and domestic production, and how resilient they are to external policy changes. This must be the way forward. Otherwise, Nepal risks building a house on sand.

 20.41°C Kathmandu